U.S.

Home U.S.

“Drill, baby drill” Trump will flop

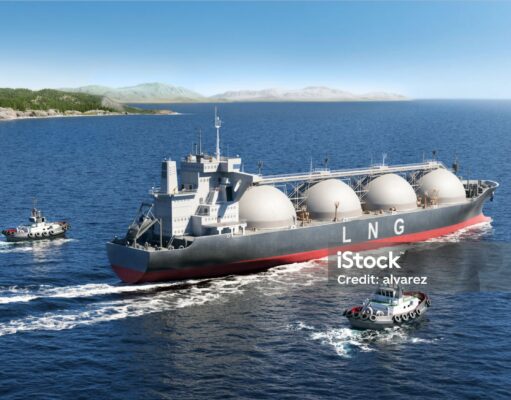
LNG export terminal

Introduction

The current oil and gas gluts and planned expansion projects will hit walls as demand around the world for fossil fuels is already on trajectories to decline.

China, the largest importer of fossil fuels, is engaged in a transition to a green economy at such a humongous pace, it is difficult to keep up with developments.

Too, China’s affordable electric vehicle (EV) global sales are on launching pads to take the world by a storm, leaving the U.S. to become a dinosaur.

U.S domestic power trends favour renewables over natural gas.

South and Southeast Asia, perceived by the liquified natural gas (LNG) industry as the next hot markets, are turning to renewables.

Lastly, Europe, South Korea and Japan, half the global LNG market, are engaged in a transition away from fossil fuels. 

Fossil fuels glut

Oil

According to the International Energy Agency, oil production will outstrip demand from now until at least 2030.  Two principal factors point in this direction.

First, growth in oil demand in Asia, aviation and petrochemicals will be more than offset by a decline in demand associated with transportation sector electrification and better fuel efficiency plus the climate action of critical fossil fuel importing jurisdictions, most notably in China and Europe, along with other countries.  More on the climate achievements and momentum of these jurisdictions follow in subsequent article segments.

Second, Guyana, Brazil and Argentina are increasing their supplies to global markets.

Hence, Trump is his worst enemy by encouraging expansion of U.S. oil production.

This could be exacerbated by a pending price war with Saudi Arabia.

For the U.S., the bottom line is the oversupply has contributed to the current price of oil, around $70/barrel, too low for U.S. expansion.  The U.S. oil industry is hesitant to expand, and more focused on shareholder returns.

For U.S. oil production to expand, the price must rise to $80 or more, becoming more unlikely due to the indefinitely long global glut.

Natural Gas

There’s already a natural gas glut, as per the conclusions of the for Institute Energy Economics and Financial Analysis (IEEFA).  This glut will get much worse, very much the result of the U.S. massive natural gas expansion projects.

Globally, the LNG supply capacity may increase to 666.5 million tonnes per annum (MTPA) by 2028. That’s greater than the IEA assessment of demand prospects for 2050, 482 MTPA.

The U.S has about 20 new LNG project terminal projects, with 4,667 km of pipelines.  If pending applications are combined with the 360 MTPA of approved projects and added to current production, the U.S. would be on a path to produced 430 MTPA of natural gas, by 2029 to 2035.

This would far exceed the current global capacity of 400 MTPA.

The U.S. expansion projects and the European gas import substitutes, post Russian invasion of Ukraine, have driven up the international price of natural gas and U.S. domestic power rates as a side-effect.

In January 2024, Biden had tried to put a temporary pause on pending LNG-related projects.  One year later,  in January 2025, Trump ordered resuming reviewal of applications for pending projects.

Trump chose to ignore the implications of increasing U.S. gas exports.

Even current capacity alone indicates there will be costly stranded assets before 2030.  Quite the risks, given the price tags of large export terminals are $15 to $25 billion, the lifespan of a export terminal is 30 to 50 years, and import terminals cost around $3 billion.

There are also the obstacles to the financing of long timelines for building LNG related infrastructures. Terminal construction can take from just under 4 to 5.1 years.

For an idea of the expenditures for pipelines, 13 of them adds up to more than $62 billion.

Further, the poor economics of the U.S. natural gas sector demise is already evident. While U.S. natural gas supplies are 78% shale gas, 30% to 40% being by-products from shale oil sites, the more productive/profitable shale U.S. oil and gas wells have been depleted. Since shale gas wells have a productive life duration of 3 years, the industry looks like its heading for another financial conundrum, a repeat of the shale industry meltdown in early 2020s.

Swelling the global supply situation, Norway, Russia, Congo, Gabon, Nigeria, and potentially Mozambique and Tanzania, are, and/or my soon be, contributing to more gas supplies on global markets.

The gas export stakeholders continue to pin hopes for larger LNG supplies to supply new markets in South and Southeast Asia,  To serve the power needs of these markets, home-grown renewables projects are the better options since they are relatively inexpensive, and construction timelines are short.

Significant, China has its own shale gas potential.  Together with China’s goal severance from fossil fuels dependencies, this will lessen the need for LNG imports.  It is estimated that China has 31.57 trillion cubic metres (1,115 trillion cubic feet) of recoverable shale gas.

Eventually, the global gas oversupply bottom line will lead to lower prices, something that threatens the viability of the U.S. shale gas sector.  These lower prices will likely last for quite some time.

Green transition is well-underway

China’s oil and gas imports decline

China, the world’s largest energy consumer, representing 25% of global oil imports and 18% of global LNG imports, is weaning off oil and gas at spellbinding rates.

China is the most electrified nation in the world and the pace of electrification continues to spiral.

No wonder, the peaks of China’s crude oil consumption and refined oil are 2025 and were 2023 respectively.  Crude oil imports declined 2% in January 2025.  By 2035, China’s refined oil products consumption is projected to drop 25-40%, based on the peak year 2023.

On natural gas, though China is the largest importer of gas in the world, consumption and emissions are destined to drop through to 2030, because gas is more expensive than coal and not green; wind and solar total capacity to-date have exceeded China’s target; coal capacity is used primarily for peaking periods; there has been a shift to supercritical coal power plants with less emissions than traditional coal facilities; and, most important, China has an overarching goal for a peak emissions deadline with an emphasis on energy independence.

China’s EVs domestic and global market expansion:

In 2024, China’s affordable and advanced tech EVs captured 60% of the global EV market, 53% of its domestic vehicle market.

Chinese EV manufacturers are now poised to conquer ALL major global markets outside North America.  The BYD momentum to-date entails manufacturing plants and projects in 7 countries and entering a new country nearly every week, with an average selling price of $16,700.

Concurrently, legacy automakers, for which China is a major market, are losing market share in the country, because they cannot compete with China’s EV’s which have better designs, prices and technologies.

The EV Trump effect

The Trump administration wants to stop attacks on gas-powered vehicles

Contributing to the demise of North American-based legacy automakers, Trump’s plan is to roll back corporate average fuel economy standards from the 2025 level to that of 2019.

The reversal on vehicle emissions will result in 25% more emissions/vehicle mile than current 2025 rules and an average fuel economy dip of 15%.  The brakes have been put on the transition to EVs.

The Trump package would also prohibit California and 13 other waiver states to adopt stricter emission rules than those of the federal government, beginning 2026.   During his first term, Trump had blocked waivers of the previous administration, but the Biden unblocked this restriction.

As for Musk, he  believes the termination of EV consumer credit will hurt Tesla’s competitors more than Tesla.  Ford claims it loses $100,000 per EV sold and EV-related 2024 loses will be well over $5 billion.

Accordingly, the Trump administration has sent clear signals to legacy automakers in U.S market to change priorities to favour lineups of more of the more profitable gas guzzlers.

The U.S. EV market share will not come close to the Bloomberg projection of 13% for 2024 or the IEA prediction of 11%.

EVs, the U.S. aside

Notwithstanding Trump’s undermining the EV sector in the U.S., by 2030, the global EV fleet will displace 3.3 million b/d (b/d) by 2030, up from 385,000 b/d in 2022.

China, renewables and keeping pace with rising electricity demand

China’s renewables have reached 50% its power supply with the installation of 357 GW of solar and wind in 2024, an 18% increase from the previous year.

The result is China’s renewables target for 1.2 TW by 2030 was reached in 2024, 6 years ahead of schedule.

Yet these achievements have not been enough since China’s electricity demand has risen faster than the economic growth since 2020.  The country’s electricity demand increased 7% in 2024, and the forecast is for an annual average of 6% through to 2027.  In addition to the electricity consumption growth associated with the manufacturing of clean tech and energy intensive industrial sectors, there are new phenomena, such as the latest highs in consumption for air conditioning and 5G networks.

The U.S and renewables

Most inconsistent with Trump’s view for America, 93% of 2024 power capacity additions stemmed from clean energy.  U.S. solar set a record in 2024, at 30 gigawatts (GW), accounting for 61% of U.S. utility scale power capacity additions for the year.

And the U.S. Energy Information Administration (EIA) predicts 2025 solar new capacity will reach 32.5 GW.  That’s far less than the 2025 EIA projection for gas at 4.4 GW of added annual capacity and lower than wind for this year at 7.7 GW.

U.S. solar additions combined with energy storage, will come to 81% of U.S. of 2025 capacity additions.

Interesting, Texas is the U.S. windpower leader and its solar sector is booming, 11.6 GW estimated for 2025.

The other 50% of global LNG markets

Elsewhere, the combined LNG imports of Japan, Europe and South Korea, which account for half of LNG demand, declined in 2023.  The descent is expected to continue through to 2030.

European gas imports were down 20% in 2024 and consumption is expected to peak in 2025.  EU gas imports trajectory is expected to continue to decline through to 2030.

Japan previously the world’s largest LNG importer, is another country where imports of gas are descending, 8% in 2023, another 9% in 2024.  Increases in nuclear and renewables capacity will assure continuation of the gas use tumble.  Since 2018, LNG imports fell 20%.

For South Korea, traditionally the largest importer of U.S. LNG, imports dropped 5% in 2023. With the planned increases in solar, wind and nuclear capacity, by 2035, LNG imports may drop by 20%.

In Southeast Asia, LNG projects are on pause with significant transitions to renewables underway, especially in Vietnam and the Philippines.

In South Asia, Pakistan proclaimed a halt to LNG projects while engaging in a radical transition to renewables.  During the last two years Pakistan installed 40 GW  of solar, extraordinary since its entire power generation capacity in 2023 was 46 GW. This profound departure from past energy policies may soon get a big boost, to the tune of $1billion in climate funds, from the International Monetary Fund.

India, like Pakistan, has no plans for plans for new LNG plants.

This spells trouble for U.S. export contracts which typically integrate flexibility for the termination of shipments.

In Canada, most of the LNG projects have been shelved, the results of high cost for terminal construction and pipelines along with public political opposition to new projects.

The takeaway

It is clear that the current oil and gas gluts will get worse with demand for fossil fuels at the precipice of a global decline.

China alone, the world’s largest energy consumer, is engaged in a mindboggling rate of electrification and decarbonization of its economy.  This will significantly reduce global fossil fuel demand, peak oil has already been reached and peak gas very soon.

China’s affordable EVs are penetrating global markets, leaving the U.S., and probably Canada, way behind in road transportation. Road transportation traditionally represents 25% of petroleum consumption.

Renewables around the globe are displacing natural gas demand.

This is even happening in the U.S, where 93% of new capacity in 2024 was attributable to renewables.  Solar and energy storage combined, will come in at over 80% of power additions in 2025.

South and Southeast Asia emerging economies are engaged in a transition to renewables.  Thus the prospects for bets on the LNG industry exports are fiction.

Ditto for South Korea LNG demand.

The European momentum on renewables, EVs, heat pumps and other decarbonization measures, are unstoppable.

Better technology at better prices are globally agnostic, as such, cannot be stopped by the phantasms of the President of the U.S.

The world is already engaged in the energy transition and all the new economic paradigms that go with it.

The Trump drill baby drill objective will flop globally and domestically.

COP29: China, Trump and the EU, each own way: Green vs. stranded fossil assets

Update Dec. 5, 2024 Chart of cargo containers with Chinese, US and European Union flags

For climate action, China has chosen long-term extraordinary innovation investments and scale to wean off fossil fuels.

The European Union (EU) is making progress for energy independence by 2027, though with some Chinese technologies.

Too, the UK and Brazil have set ambitious climate targets

The U.S., Trump administration will enhance paths towards stranded fossil fuel assets. The private sector will continue floundering on clean tech innovation and base performance on the short-term, quarterly reports.

Canada will emulate the U.S.

China

China spent $676 billion on clean tech in 2023, over double that of any other nation.

The good news is that China’s power emissions may peak by 2025, ahead of its 2030 target and the first annual decline since 2016. Should China succeed in plateauing emissions in 2025, the Paris Agreement target to halve emissions by 2030, could have been a possibility, if it weren’t from Trump.

This potential appears unimaginable since China accounted for 30% of global emissions in 2022, 11 billion tonnes.

China’s 2024 drop in annual emissions is anticipated to be about 7.2% or 8.2%.

The bad news are potential impacts on economies outside China regarding their clean tech manufacturers competing with much more affordable and more advanced Chinese exports.

There appears to be a pattern for China’s clean tech successes, high up front government support for research and development plus oversupplying the domestic Chinese market.  This formula has had mixed consequences.

China’s oversupply of clean tech industry typically achieves excellent economies of scale for offering low prices, but often results in profit declines, or even losing money, due to fierce competition in the domestic market.

To make up for the domestic low margins, prices for Chinese export markets are set to be both profitable and affordable choices in these markets.

European Union

The European Union, post Russian invasion of Ukraine, like China, has an agenda to sever dependence on fossil fuels. The EU aims for energy independence via a green transition by 2027.

While there was a 911-like spike in LNG imports from the U.S. immediately after the invasion, thanks to intensive emphasis on renewables, heat pumps, efficiency and other measures, EU gas imports were down 20% in 2023 and anticipated to peak by 2025.

Electric vehicle (EV) sales trends indicate a displacement in European oil consumption of 3.3 million barrels/day by 2030.

U.S. and Canada

Trump promised to pull out of the Paris Agreement.

Though the Inflation Reduction Act (IRA) and Bipartisan Infrastructure Law (BIL) have been outstanding in supporting the building of clean tech factories, EV purchases and the installation of home energy saving solutions, e.g. heat pumps, and solar panels, Trump wants to water down these milestone laws to suit his agenda.

Nonetheless, Trump will have to take into account that in 2023 the clean energy sector, including storage and EV charging, came in at 40% of U.S. energy jobs, with a 200% growth in that year.

The EV and battery projects announced and associated with the Inflation Reduction Act and Bipartisan Infrastructure Law will create of 201,900 jobs.  This sector could generate another 931,000 jobs.

Still, since the U.S. innovation gap with China widened even with the original IRA and BIL in place, expect that gap to grow when Trump unbelievably dilutes the legislation.

Trump referred government backing of the green economy as a “green new scam.”

Further contributing to the innovation gap, emission standards across all sectors will become more lenient.

Most notably, the overriding energy themes will be in “drill, baby drill,” for increasing oil and gas production.

What will Trump do when global fossil fuel demand peaks and U.S. clean tech jobs outnumber oil industry employment?

Sadly, Canada will follow in U.S., as always, and continue to be a fossil fuel exporting nation.  The next likely Prime Minister, Pierre Poiliève, will make sure of that.

UK and Brazil step up at COP29

At COP29, the UK pledged to reduce emissions by 81% by 2035 from 1990 levels and Brazil has prepared a comprehensive climate plan for a 59% to 67% GHG reduction by 2035 based on 2005 levels.

Electric Vehicles and batteries

China’s dominance in affordable electric vehicle (EV) and battery sectors are prominent examples of technological leadership and the Chinese oversupply business models.

At first glance, one might get the impression that China is an unlikely leader in these sectors.

Compared to Western economies, China has considerably fewer cars, vans, buses, freight and other trucks per 1,000 inhabitants at 231, very low compared to the U.S. 908; Canada 790; Germany 628; and  U.K. 600.

In part, low vehicle ownership in China is a consequence of being the global leader public transit. China has 46,000 km of high-speed rail, 50 subway systems with over 10,000 km of track, substantial light rail and had 455,000 e-buses on its roads in 2022.

Yet, with EVs having reached 53% of the Chinese vehicle market in September 2024, China represented 69% of the global EV registrations in 2024, up until October.  That’s because Chinese EVs are considerably more affordable than EVs in other countries.

China’s EV tech lead goes back to the 1990’s when China started to invest in EV research.  Back then, China had realized Chinese manufacturers of internal combustion engine vehicle (ICEV) models could not compete in export markets that are too overcrowded with competitors.

Thereupon, China developed a complex compilation of measures that pushed manufacturers towards producing New Energy Vehicles (EVs), the consequences being manufacturing of ICEVs became more expensive to produce and EVs less expensive.

Today, additional more compelling contributing factors to Chinese affordable EVs and batteries include government support for quickly getting over the time hump to get a return on investment. Overall, China’s EV financing covers innovation, development, minimizing production costs and start-ups.

China’s holistic long term vision has been a key to reducing EV battery costs.  China has invested more on battery research than all other nations combined and has a plethora of EV R & D programs.

Unimageable in Western economies, China’s CATL, the largest battery producer in the world, has 20,000 employees dedicated to R & D.

BYD, the largest EV manufacturer in China and second biggest battery producer, is a rare integrated EV and battery firm making most parts in-house.  These achievements are thanks to its 900,000 employees, of which more than 110,000 are R & D staff.

By early 2022, China accounted for 80 percent of global battery production capacity and controls, 75% of battery cell manufacturing, 90% of anode and electrolyte production, 60% of battery component manufacturing, and refining for more than half of global lithium, cobalt and graphite.

The battery technology-related savings have manifested into 95% of Chinese made EVs equipped with the less costly lithium iron phosphate (LFP) batteries.  LFP batteries are nearly exclusively manufactured in China.

Outside China, NMC batteries (lithium-nickel-manganese-cobalt-oxide) are typically used.

Compared to the NMC batteries, LFP batteries are cheaper to manufacture, have higher stability and are easier to recycle.

However, on performance, LFP batteries are not yet as good as lithium-ion ones.  But technological advances are in the process of closing the performance gap.

CATL and BYD alone, have 90% of the LFP market.

The results are battery costs are about 18% less in China than elsewhere.  This is critical for the pricing of an EV since the battery typically comes in at 40% of an EV’s cost.

However, until now, China’s LFP batteries have been destined for the more affordable entry level small low- to mid-cost models.

Hyundai is about to change all that, challenging China’s LFP cartel with an ultra-high capacity 300 Wh/kg LFP battery to be produced without Chinese components by end 2025.  Average Chinese LFP battery capacity is 200 Wh/kg.

If Hyundai succeeds in its LFP development plan, it will have a LFP battery with longer range than the typical NMC battery and would be the first LFP battery for high performance EVs.

If all goes according to plan, Hyundai may be able to produce affordable EVs with LFP batteries for both entry level and performance models, with impressive range and not subject to tariff barriers.

Also in progress, BYD is constructing a factory for third generation batteries, sodium-ion batteries, for scooters and micro vehicles, for starters.  BYD believes it could eventually produce sodium-ion batteries that will be less than the cost of LFP in the long term.

CATL is working on its improved new enhanced version of sodium-ion batteries for small and short range vehicles and China’s Chery will have a factory for the fourth generation, solid-state batteries.

As well, China’s EVs benefit from better economies of scale associated with oversupplying. Chinese EV manufacturers bet attractive pricing will create demand to meet supply.  Oversupply may be an understatement as China’s 200 EV manufacturers will have launched about 110 EV models by end 2024.  With all the competition, the average domestic profit margin is slim, averaging 5% in 2023, with some models sold below cost.

As indicated above, the profits are made on exports, while still maintaining a price advantage.  The BYD lineup average price is $30,000.

While the U.S. and Canada have imposed 100% tariffs on Chinese EVs, BYD is entering a new foreign market nearly every week, launches about 10 new models/year, and has an operating manufacturing plant in Thailand, plus facility projects in Mexico, Hungary, Turkey, Brazil and Indonesia.

These are important considerations, since the revenues of legacy automakers depend on global markets, not North America alone.

Legacy EV and battery manufacturers outside Asia cannot compete with the scale, pace of innovation and/or vertical integration of their Asian competitors.

Legacy firms depend on a plethora of external suppliers.

All the more for making the future of Western legacy automakers uncertain.

Tariffs and other barriers to affordable EVs

The U.S. and Canada 100% tariffs on China’s EVs, batteries and components will boomerang regarding a growing innovation gap and legacy automakers’ competitivity in critical global markets.

Not bothered by the United States-Mexico-Canada Agreement on trade, Biden and Trump intend to keep Chinese EVs made in Mexico out of the U.S.

Since the U.S. also has a trade agreements with Morocco and South Korea, many Chinese EV components investors had been planning to build plants in these countries.

A Trump reworking of the Inflation Reduction Act and Bipartisan Infrastructure Law, upon which the Moroccan and South Korean projects are premised, may see the aforementioned investments put on pause.

The Biden administration has already implied that Chinese EVs manufactured elsewhere would not be eligible for $7,500 consumer credit applicable to North American built vehicles.

Trump may put the final nail on this escape route.

The Trump additional 25% import tariffs for all goods from Canada and Mexico might apply to Canadian EVs and batteries too.

Contrasting the U.S. an Canada, the European Union has manufacturer-specific trade barriers on Chinese EVs, the EU varying tariffs range from 8% to 35%, on top of an existing 10% duty.  The highest tariff is aimed at SAIC Motor Corp, likely because the company is state-owned.

The EU doesn’t want to set the tariffs too high because the EU hopes to attract China’s manufacturers to invest in factories in the EU.  Production of Chinese EVs in Europe would remove tariffs and many Chinese EV manufactures are doing just that.

In addition to the BYD EV plants planned for Hungary and Turkey, other Chinese EV stakeholders, such as Geely vehicles and CATL, are engaged in major investments in Europe.

Even with the EU tariffs, many Chinese EV imports will still be somewhat more affordable than their European competitors.

The European Commission (EC) concluded that the average Chinese EV battery electric vehicle (BEV) imports cost 32% less than European EVs in 2023.

The 2024 prognosis is that China’s EV imports will come in at 25% of the European EV market share.

A large portion of these imports are Tesla, Dacia and BMW EVs.

Legacy automakers

The China advantage spells trouble for EVs produced by legacy automakers.

Battery projects in Western economies may be outdated before production begins.

Better technology and better prices cannot be stifled by protectionism.

Many legacy automakers have not gotten over the hump for a return on investment.

In June 2024, Ford claimed it loses $100,000 for every EV sold, its EV division lost $4.7 billion in 2023 and expected losses to hit $5.5 billion in 2024.  Thus, Ford plans to offer more of the more profitable plug-in hybrids.

Meanwhile, GM is mumbling about offering different battery chemistries and enlarging its plug-in hybrid lineup.

Volkswagen, the largest German employer with 10 factories in the country, is experiencing economic troubles too and looking to plug-in hybrids as the way forward.

In late October 2024, Volkswagen announced it will be shutting down 3 plants in Germany and cut wages by 10% for 140,000 employees.

Among other things, Volkswagen cited a drop in third quarter 2024 profit levels by 42% associated with lower then projected, or insufficient, EV sales, to recover the high EV transition costs; increased competition from European EV imports from China; and sharp declines in the Volkswagen market in China, where EV sales now exceed ICEVs.

Since traditionally 40% of Volkswagen sales have been in China, the deterioration of the Volkswagen market in China constitutes a heavy blow for the company.

Likewise, BMW and Mercedes Benz are dependent on the Chinese market, for 32% of global sales and 28% respectively.

This puts Volkswagen, Mercedes Benz and BMW in a conundrum.

Germany opposed EU tariffs on EV imports from China.

Oversupply in renewables

China is determined to reduce its dependence on fossil fuel imports while Trump aims to increase oil and gas production.

Accordingly, the China clean tech oversupply business model applies to the solar panel, and wind turbine sectors.

In the China’s wind sector, production overcapacity during 2022 and 2023 brought about low domestic market profit margins, while in the U.S. and Europe, the margins were 2 to 3 times higher.

Consequently, the Chinese turbines prices in Europe and the U.S. were lower than their European and U.S. competitors.  Six of the 10 top windpower producers are Chinese.

For solar panels, despite China’s mindboggling increases in the annual solar installation rate, China’s solar manufacturers were caught with an oversupply having exceeded China’s storage and transmission capacity.

In the coming two years, the Chinese solar modules manufacturing capacity may actually double world demand.

As is the case with the Chinese EV sector, excessive renewables competition within China has led to unprofitably low domestic prices, compensated by exports of more profitable and affordable exports.

Trump’s proposed 20% tariffs on all solar and wind imports from China could affect the prices of renewables in the U.S.

The takeaway

China, the EU, the UK and Brazil will accelerate weaning off fossil fuels, leaving the U.S., and Canada too, to increase the production of these fuels as the market for these fuels dwindles.

China will persist in manufacturing more clean tech, solar, wind, EVs, batteries/storage, plus electrifying its industries at levels greater than the rest of the world combined.

For the U.S., action on climate change to compete with China, will take inconceivable huge hits with Trump, while fossil fuel production will be administered steroids.  The U.S. clean tech private sector will continue to lag on innovation, constrained by an investment community which only understands  quarterly reports.  The U.S. will continue to lose ground on clean tech leadership.

Canada has much to lose, especially with Conservative Pierre Poiliève, the likely next Prime Minister, aligned with Trump on denial of climate change, increasing oil and gas production and many other issues.

The EU seeks win-win formulae with rational environmental and economic considerations.  The EU may show the way forward.

China, the EU, UK and Brazil will stand out as global climate leaders.